Italy 2026: why international capital is choosing Italian real estate
In the first half of 2026 real estate investment in Italy exceeded €7 billion, with foreign capital accounting for 67–75% of volumes. Behind the numbers lies a deeper shift: value is created by transforming assets, not simply holding them.
Italy · October 2026
A record half-year for foreign capital
2026 opened with the strongest first half in years for the Italian real estate investment market.
According to Patrigest | Gabetti Group’s Research & Data Intelligence, the sector attracted €7.3 billion in the first six months, up 37% on the same period of 2025. JLL, which includes developments and share deals, estimates about €7.8 billion (+34%).
The most telling figure is where the money comes from: 67% of volumes were foreign according to Gabetti, 75% according to JLL — in both cases above the ten-year average. By volume invested the leading countries are the United States, Qatar and Spain; by number of deals the United States, France and Spain.
2025 had already closed as the second-best year on record: €12.5 billion (+23%), with 58% foreign capital (Cushman & Wakefield).
- €7.3 bn
- Investment H1 2026
- +37%
- vs. first half 2025
- 67–75%
- Share of foreign capital
- €12.5 bn
- Full-year 2025 (+23%)
Where the capital goes: retail, logistics, living
The mix of investment tells the story of a market rebalancing itself.
Retail is back at the centre with about €2.4 billion (+116%), the best first half ever recorded for the sector. Logistics reached €1.2 billion (+48%). Hospitality held just under €1.2 billion: down 10% from an exceptional 2025, but with Milan in the lead (30% of volumes) and luxury and upper-scale hotels taking 85%.
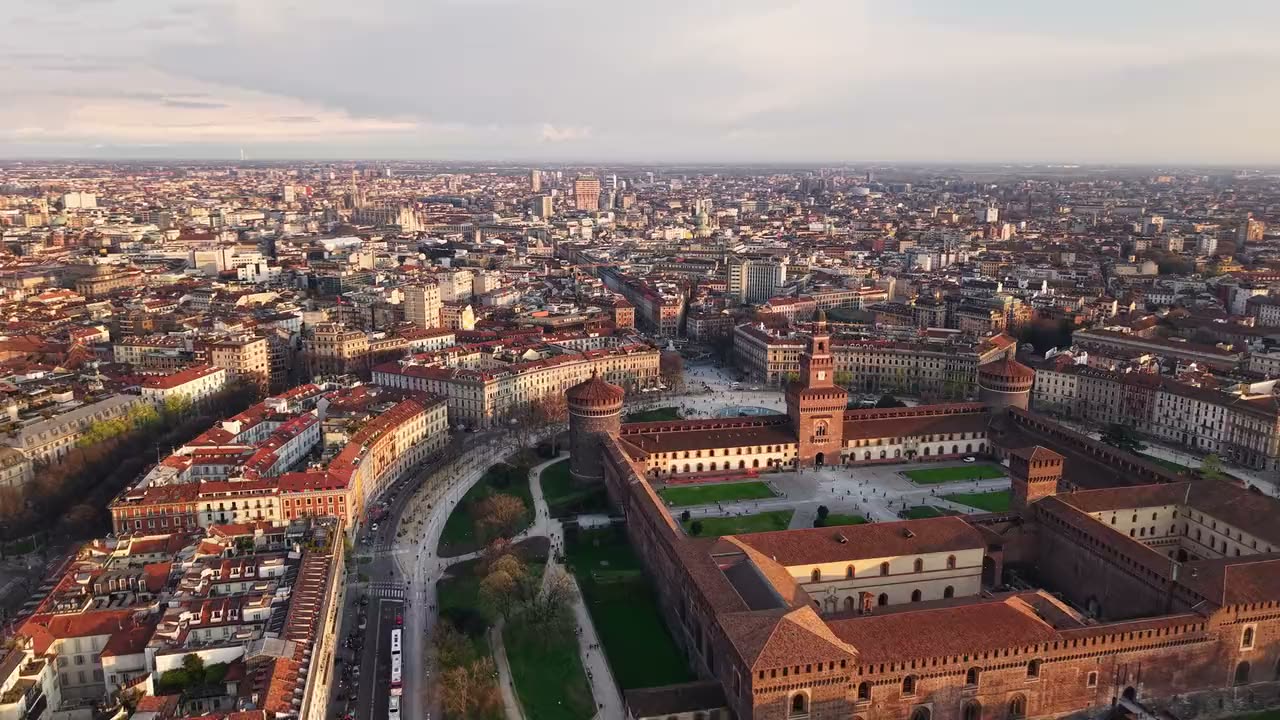
Living — residential development and student housing — is the fastest-growing segment: +89%, to about €650 million across 19 deals, more than 60% of them in Milan and its metropolitan area. Build-to-sell accounts for 48% of this volume.
Offices, at about €650 million (-29%), remain concentrated in the Milan and Rome CBDs (80% of the total). Alternative asset classes, led by data centres, reached €750 million (+140%).
- Retail
- Logistics
- Hospitality
- Living
- Offices
- Data centres
- +89%
- Living (residential and student housing)
- 60%+
- Of living volumes in Milan
- 4.5%
- Prime multifamily yield (JLL)
Why Italy remains attractive
Three factors explain international investors’ confidence.
Yields. Italian prime yields remain competitive with other European markets: 4.0% for Milan offices, 4.5% for multifamily residential, 5.3% for logistics, 6.5% for shopping centres (JLL, Q2 2026). After the repricing of the previous two years, Cushman & Wakefield expects yields to stabilise during 2026.
Product. Italy offers a vast building stock, often dated and under-used: buildings in excellent locations that need energy retrofits, change of use or subdivision. This is where demand for value-add capital concentrates.
Context. Milan confirms its role as a European hub for offices, hospitality and living; the tax regime for new residents keeps supporting demand for prime homes from international families and entrepreneurs.
From holding to transforming
The message from market operators is clear. For Luca Dondi dall’Orologio, CEO of Patrigest, the defining feature of this phase is the “structural transformation of demand”. For Daniele Martignetti, CEO of Great (Gabetti Group), value creation depends “less and less on simply holding the asset”.
Cushman & Wakefield expects a gradual return of core capital to prime, well-located assets in 2026, with growing selectivity towards ESG-compliant properties and lower-risk profiles.
In other words: the market rewards those who can find the right asset, structure the operation and manage every phase — from acquisition to exit. The macro backdrop (geopolitical uncertainty, inflation, tighter monetary policy) makes this capability even more important.
What this means for investors.
Italy is back at the centre of international capital strategies, but 2026 is not a market where you can simply buy and wait. The operations that work are built on rigorous analysis, a credible Business Plan and active management of development.
Selection
The assets attracting capital are prime, well located and with clear transformation potential.
Living in Milan
Residential development is the fastest-growing segment and concentrates in the Lombard capital.
Management
Value is created in the design, construction and exit phases — not in holding alone.
Sources and methodology
Patrigest | Gabetti Group, Research & Data Intelligence, H1 2026 (via idealista/news, August 2026); JLL, Italy Capital Markets Q2 2026; Cushman & Wakefield, Italy Real Estate Market Overview H2 2025 & Outlook 2026. Figures are scenarios based on assumptions and do not constitute a promise or guarantee of results.
Read the source